What an analyst call reveals that a marketing deck won’t
Last reviewed
An analyst call reveals what a marketing deck hides: the operational gaps behind growth claims. Investor questions probe conversion, capacity, payer mix and unit performance months before they show in patient satisfaction scores. Hospital growth and communications teams should sit in on those calls and build the same scrutiny into their own reporting.
Two documents, two audiences
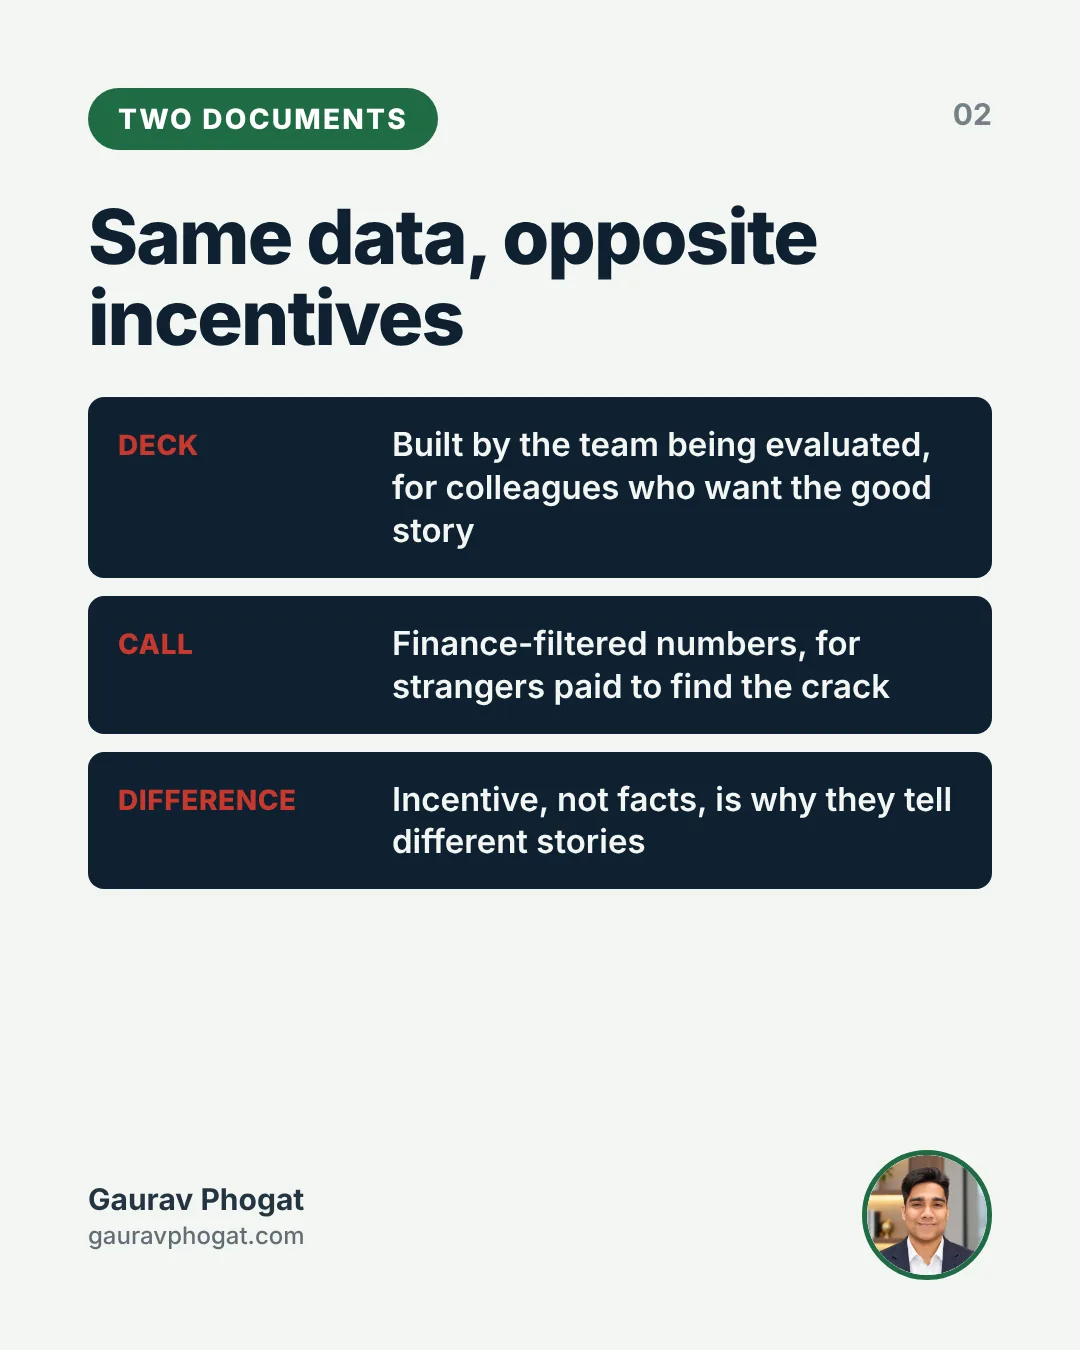
Every hospital group of any size produces two very different accounts of itself in the same quarter. One is the internal marketing deck: the slide pack presented to leadership showing campaign performance, brand tracking, service-line growth, all framed in the most favourable available light because that is, largely, what the format rewards. The other, for listed or investor-backed groups, is the earnings call and the analyst Q&A that follows it, where the same underlying numbers are presented to an audience whose entire professional incentive is to find the crack in the story.
See every healthcare PR and communications guide in one place.
The two documents are often drawing on the same underlying data. What differs is what happens to that data on the way to the audience. A marketing deck is built by the team being evaluated on its own performance, presented to colleagues and superiors who have every institutional reason to want the good story to be true. An analyst call is built around numbers that have already been through a finance and investor-relations filter, presented to strangers who are paid to assume the good story is not entirely true until proven otherwise.
That difference in incentive, more than any difference in the underlying facts, is why the two documents so often tell different stories about the same quarter.
Why decks are built to smooth and calls are built to probe
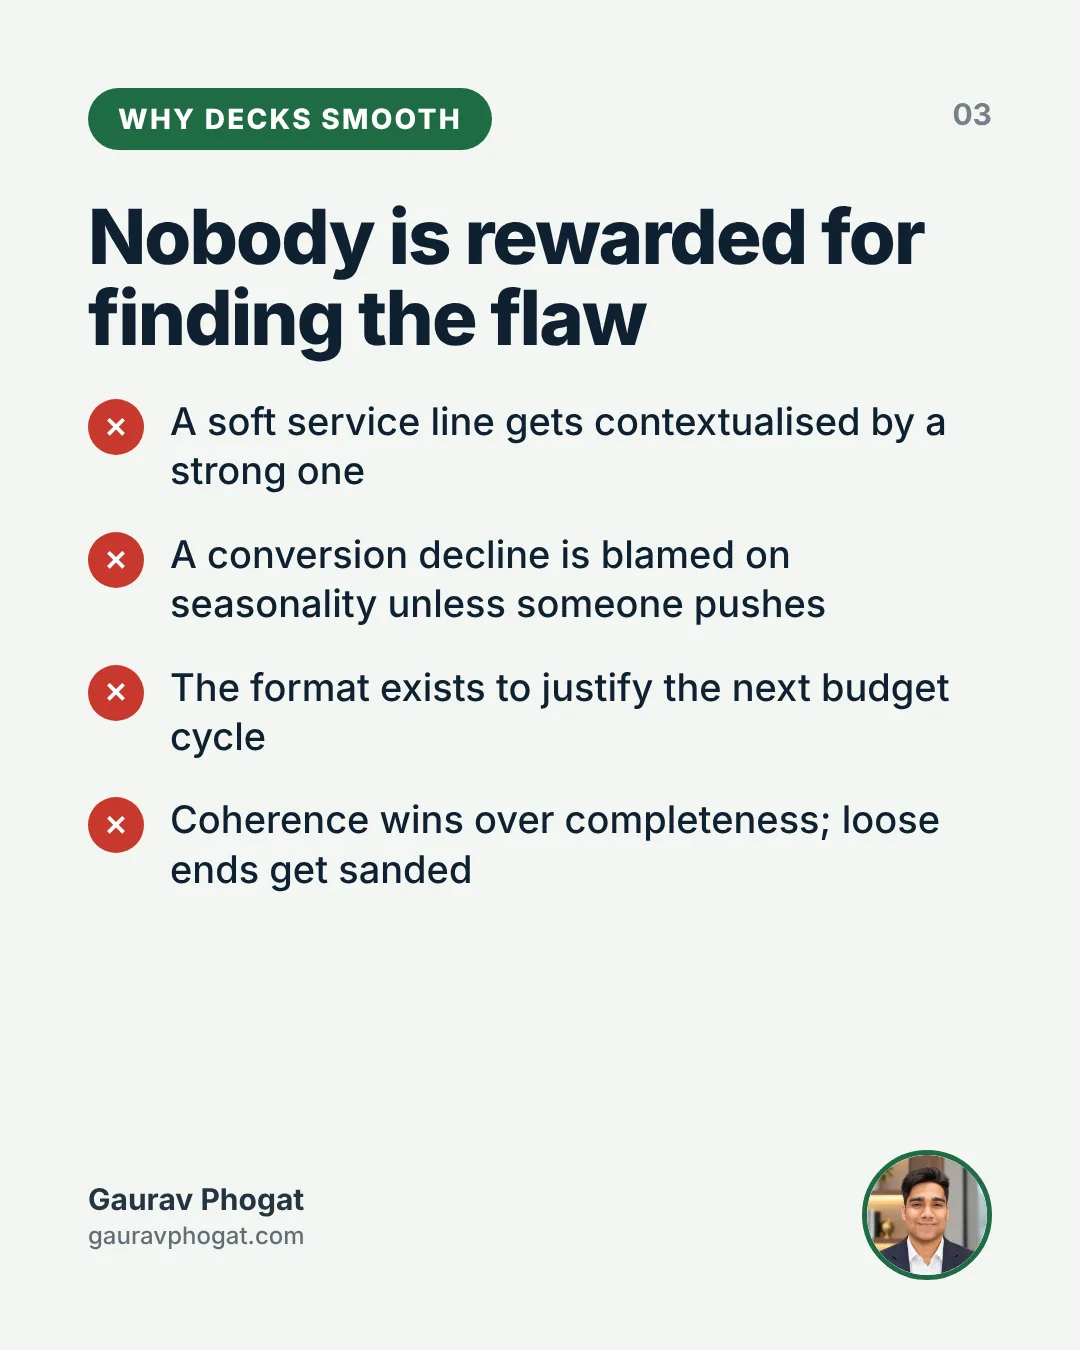
A marketing deck’s job, in most organisations, is to make the case for what the function did with its budget and what it plans to do with the next one. It is not usually presented as fraudulent or dishonest (the numbers are typically real), but the framing choices are made by people with a stake in the framing. A soft quarter in one service line gets contextualised by a strong quarter in another. A decline in conversion gets attributed to seasonality unless someone in the room specifically pushes back. Nobody in the room is professionally rewarded for finding the flaw in their own presentation.
An earnings call inverts every one of those incentives. Analysts are evaluated on the accuracy of the picture they build of the company, not on how agreeable they are in the room, and their compensation is indirectly tied to catching problems before the market prices them in. A question like why occupancy in a particular facility declined sequentially, or why average revenue per occupied bed moved against the direction management’s own guidance implied, is not asked to be difficult. It is asked because the analyst’s job depends on not accepting the smoothed version of events.
The result is that an earnings call routinely surfaces questions nobody in an internal marketing review would have thought to ask, simply because nobody in that internal room is structurally incentivised to ask them.
The questions marketing decks never ask
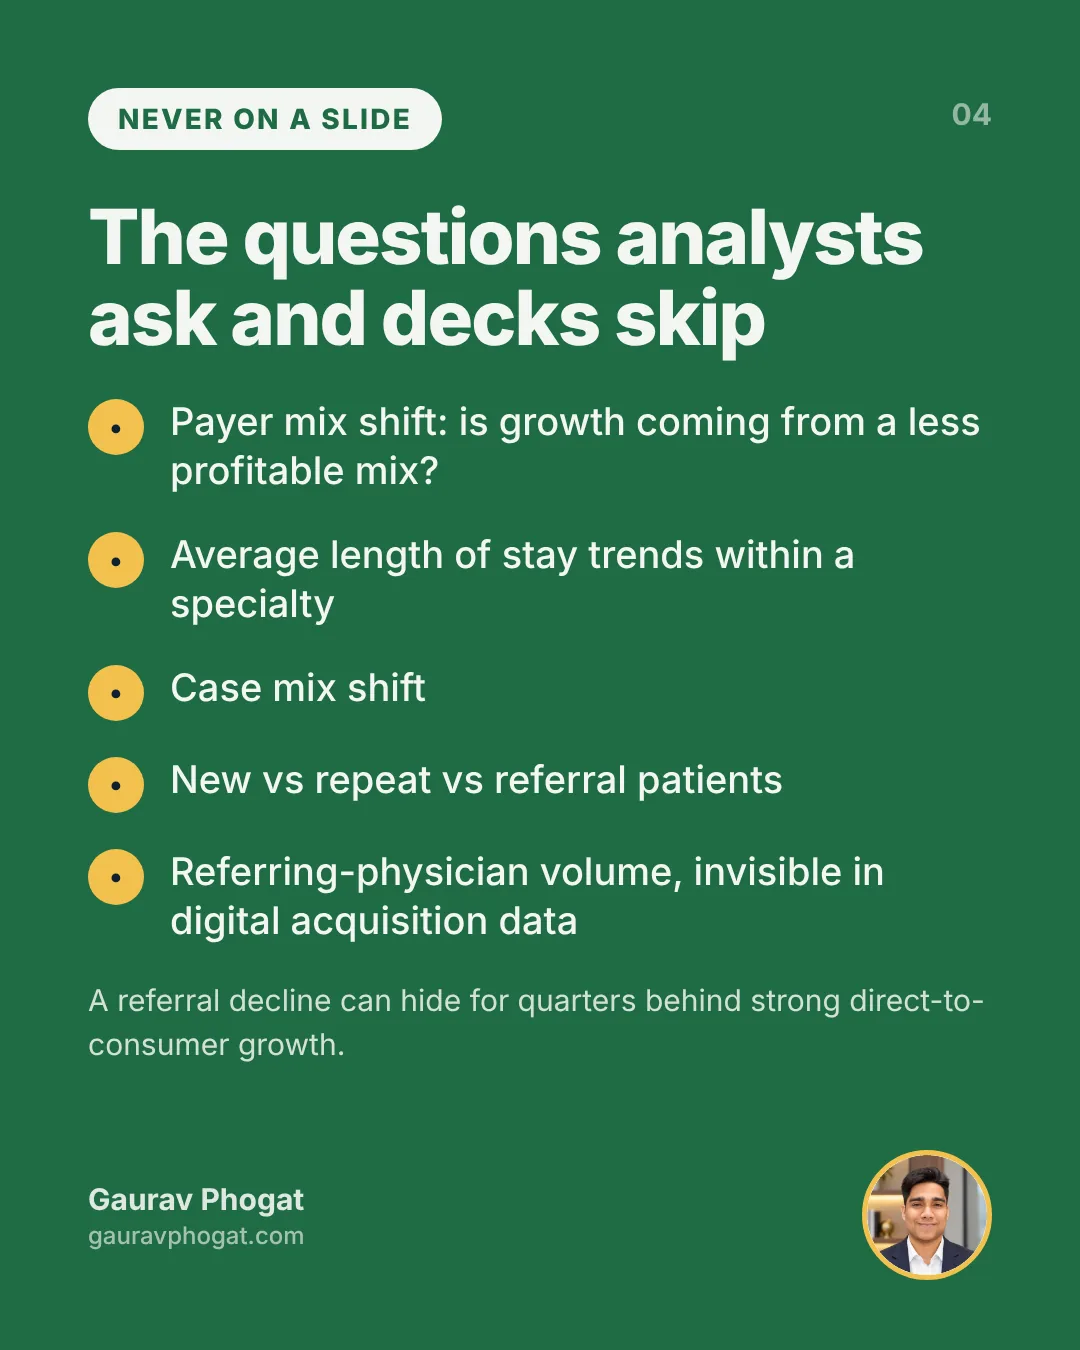
Certain categories of question show up reliably on analyst calls and almost never in internal growth reviews. Payer mix shift (whether growth is coming from a more or less profitable mix of patients than the prior period) is a standard analyst question and a rare marketing-deck slide, because payer mix is a finance metric that most marketing functions do not track even though it directly affects the quality, not just the quantity, of the growth they are claiming credit for.
Average length of stay trends, case mix shift within a specialty, and the ratio of new patients to repeat and referral patients are similarly common on calls and rare in decks. Referral network health in particular is a signal marketing functions are often slow to track directly, because it does not show up in digital acquisition data at all. A decline in referring-physician volume can be masked for several quarters by strong direct-to-consumer growth, and an analyst asking about the split between the two is often the first person in the organisation to ask the question out loud.
None of these are exotic metrics. They are ordinary operating questions that a marketing function, left to its own reporting cadence, tends not to prioritise, because none of them are optimised for by a campaign dashboard.
The discipline of being asked why twice
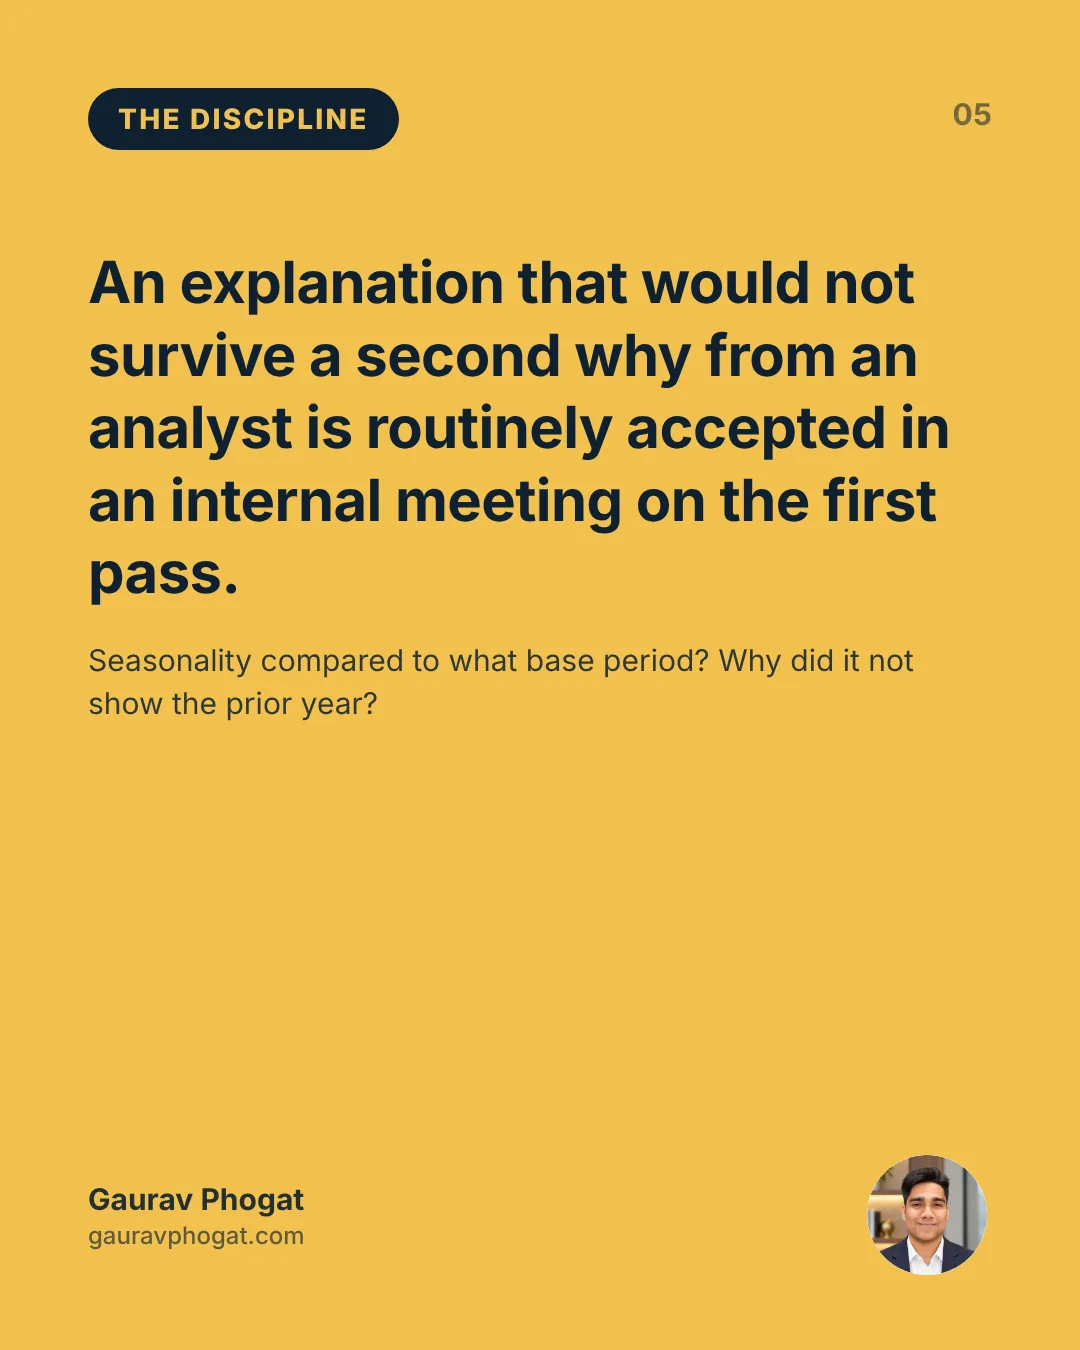
The single habit that most distinguishes investor-facing communication from internal reporting is that analysts do not accept the first answer. A management team that attributes a soft quarter to “seasonality” on an earnings call will typically be asked a follow-up (seasonality compared to what base period, and why did that seasonal pattern not show up the prior year?) and has to have an answer ready that survives the second question, not just the first.
Internal marketing reviews almost never apply this discipline to themselves. An explanation that would not survive a second “why” from an analyst is routinely accepted in an internal meeting on the first pass, because the audience in the room is not structurally motivated to push. Growth and communications functions that adopt the analyst habit internally, building every explanation for a soft number as though it has to survive one more question, tend to catch real problems a full cycle earlier than functions that stop at the first plausible explanation.
This is not a call to make internal reviews adversarial for its own sake. It is a call to borrow the specific discipline of not letting a convenient explanation stand unexamined simply because nobody in the room has an incentive to press it.
Why growth teams should sit in on the calls
In most hospital groups, the earnings call is treated as investor relations’ and finance’s territory, with growth and communications functions receiving a summary afterward, if they receive anything at all. This is a missed opportunity, because the call is one of the few forums in the organisation where its own numbers are questioned by someone with no institutional stake in the answer being reassuring.
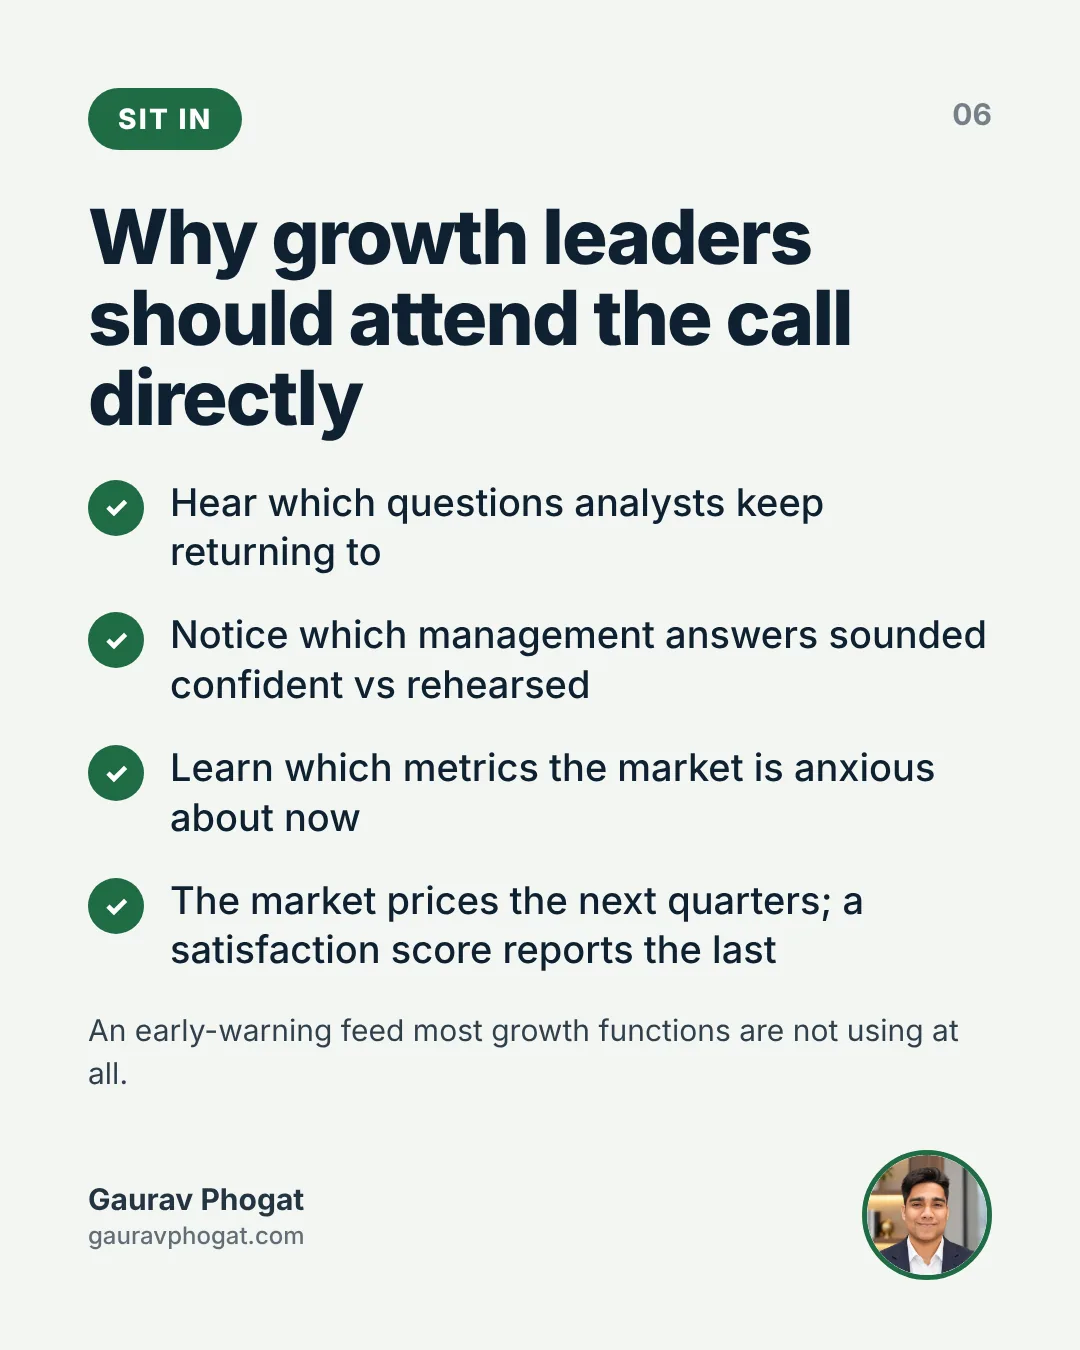
A growth or communications leader who sits in on the call directly, not through a secondhand summary, hears which questions the analysts keep returning to, which answers from management sounded confident versus which sounded rehearsed, and which metrics the market is currently most anxious about. That is a genuinely different, and often earlier, signal than anything a brand tracking survey or a patient satisfaction score will produce, because the market is pricing in expectations about the next several quarters, while a satisfaction score is reporting on the quarter that already happened.
Treating the call as a listening exercise, not just a reporting obligation for finance, is a low-cost way to get an early-warning feed that most growth functions are currently not using at all.
Building the feedback loop
The practical version of this is a short, structured process run every quarter: growth and communications leadership review the analyst questions and management’s answers within a few days of the call, specifically looking for any question that did not have a fully confident answer in the room, or any metric an analyst pressed on more than once.
Those flagged items become inputs into the next growth planning cycle, treated with the same seriousness as an internal red flag, rather than filed away as an investor-relations matter that has already been closed out once the call ends. A payer mix question that made management visibly pause on the call is worth a genuine internal investigation, even if the internal marketing dashboard shows nothing unusual, precisely because the dashboard and the analyst are measuring different things and the analyst’s question is often the earlier signal of the two.
Over several quarters, this builds a habit that is difficult to replicate any other way: a standing discipline of treating outside scepticism as free diagnostic information rather than as a quarterly formality to be managed and moved past.
What a marketing deck optimises for, and what a call forces you to defend
A marketing deck optimises for a clear narrative that justifies the next budget cycle. That is a legitimate function of the format, not a flaw in it, but it means the deck is structurally biased toward coherence over completeness. Loose ends get smoothed rather than flagged, because a deck full of open questions does not make the case it is meant to make.
An earnings call optimises for something closer to the opposite: it forces management to defend the loose ends specifically, because that is where the analyst’s questions are aimed. A growth function that only ever sees its own numbers through the deck format never has to build an answer for its own weak points, because nobody in that format is asking. The call is where that muscle actually gets exercised, which is exactly why it is worth treating as more than a finance obligation.
A practical process
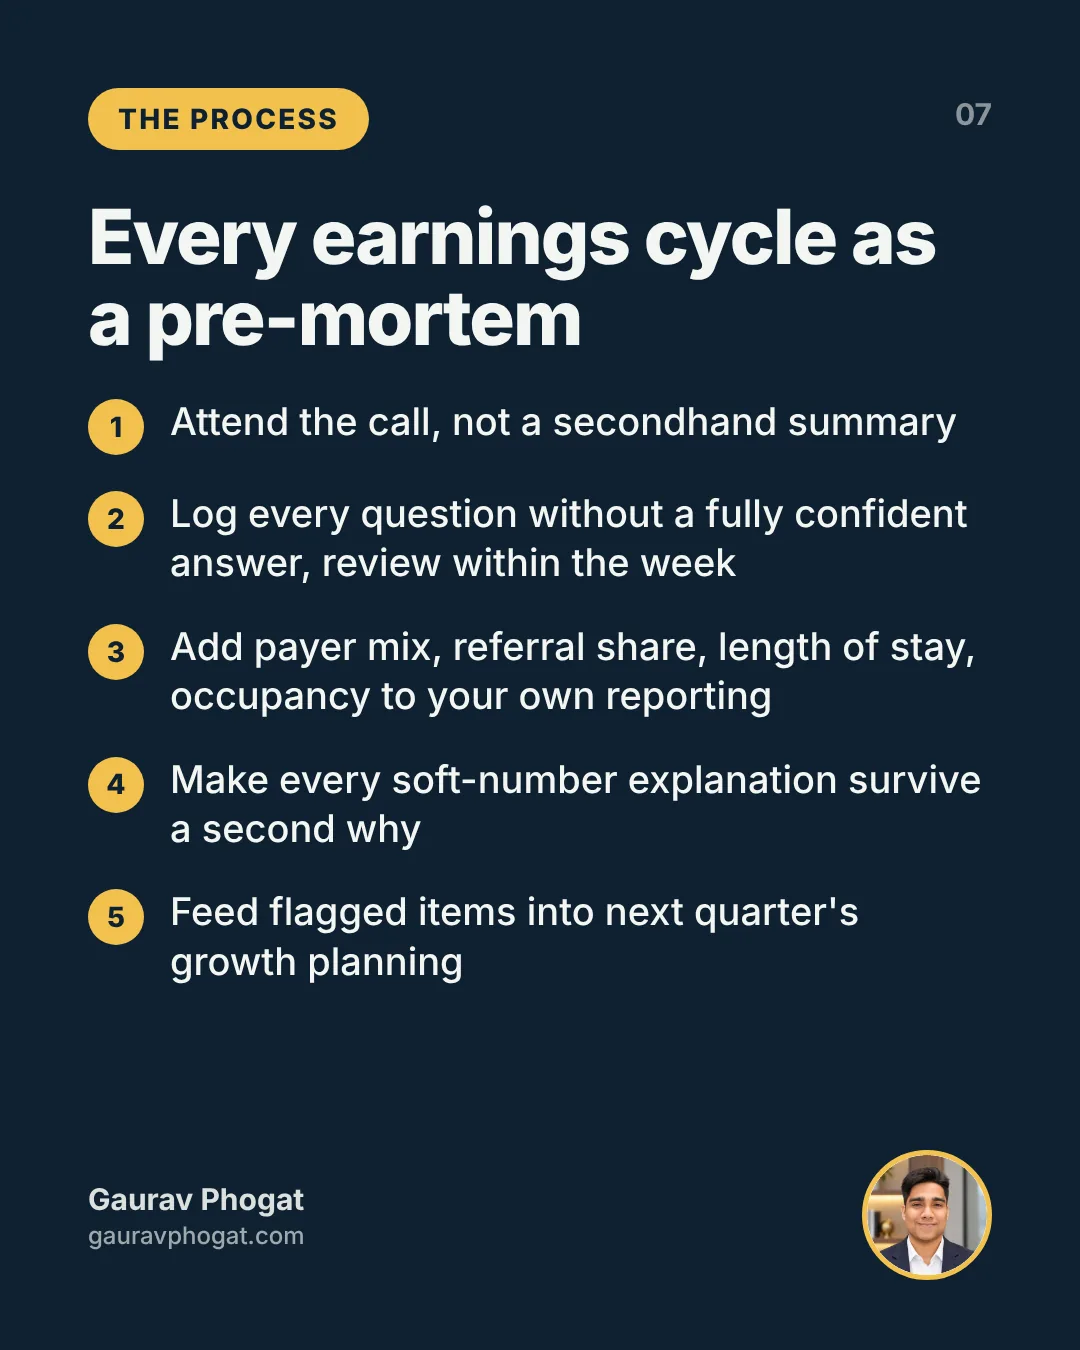
Treating each earnings cycle as a pre-mortem for the brand and growth plan, rather than a quarterly formality, comes down to a small number of habits repeated consistently:
- A growth or communications leader attends the call directly, not via a secondhand summary.
- Every analyst question that did not get a fully confident answer is logged and reviewed within the week.
- Metrics analysts keep returning to (payer mix, referral share, length of stay, occupancy trend) get added to the growth function’s own regular reporting, not left solely to finance.
- An explanation for a soft number has to survive a second “why,” internally, before it is accepted.
- Flagged items feed directly into the next quarter’s growth planning, not into a filed-away investor-relations note.
A marketing deck will tell you the story the organisation wants to be true. An analyst call tells you which parts of that story a sceptical stranger is not yet willing to believe. That gap, tracked consistently, is one of the earliest warning systems a hospital group’s growth function has, if it is willing to listen to a conversation it did not design.
Further reading from primary sources
- AMEC: Barcelona Principles 4.0: the global standard for communication measurement.
- IBEF: Healthcare industry in India: sector overview and growth drivers.
Questions people ask
Related reading: The doctor as spokesperson, not the marketing department; Why hospital press releases get ignored; and The board deck that finally got digital funded.
The difference comes down to incentives rather than access to different data. An internal marketing deck is typically built by the team being evaluated on its own performance and presented to colleagues who have an institutional interest in the good story being true, so framing choices tend to smooth over rough numbers rather than flag them.
Common examples include payer mix shift, which affects the profitability of growth even when patient volume looks healthy; average length of stay trends within a specialty; case mix shift; and the split between new, repeat and referral patients, particularly referring-physician volume, which does not show up in digital acquisition data at all.
Yes, directly rather than through a secondhand summary from investor relations. The call is one of the few forums where the organisation’s own numbers are questioned by someone with no institutional stake in a reassuring answer, and a growth or communications leader who listens firsthand picks up on which questions analysts return to, which management answers sounded confident versus rehearsed, and which metrics the market is currently anxious about.
A patient satisfaction score reports on a quarter that has already happened, aggregated and smoothed across a large sample, which means a real problem usually has to persist for some time before it moves the number enough to be noticed.
It means building a routine process, run every quarter, where growth and communications leadership review the questions analysts asked and how confidently management answered them, specifically looking for any question that did not get a fully assured response or any metric an analyst pressed on more than once.
Because internal reviews rarely apply a second round of scrutiny to an explanation that sounds plausible on first hearing, while analysts routinely do. A soft quarter attributed to seasonality, for instance, is likely to be met with a follow-up asking what the comparison base was and why the same seasonal pattern did not appear the year before.
The specific mechanism, a public earnings call, only applies directly to listed groups, but investor-backed private groups usually go through an equivalent process with private equity or institutional investors during periodic reviews, and the same dynamic of outside scepticism surfacing weaknesses an internal deck would smooth over applies there as well.
Payer mix refers to the proportion of patient volume coming from different payment sources or categories, and it affects the profitability of growth independently of how much volume is actually growing.
The review should happen on the same cadence as the calls themselves, typically quarterly, and should occur within a few days of each call while the questions and management’s responses are still fresh, rather than being folded into a broader annual planning exercise months later.
Not inherently. A marketing deck’s job is to make an honest case for what a function accomplished and what it plans to do next, and reasonable framing choices (leading with a strong result, contextualising a weak one) are a normal part of that format rather than a form of dishonesty, provided the underlying numbers are accurate.
The biggest missed opportunity is functional: the call is treated as the exclusive territory of finance and investor relations, with growth and communications functions receiving, at best, a brief summary after the fact and often nothing at all.
Read my takes first in Google Search